In 30 seconds
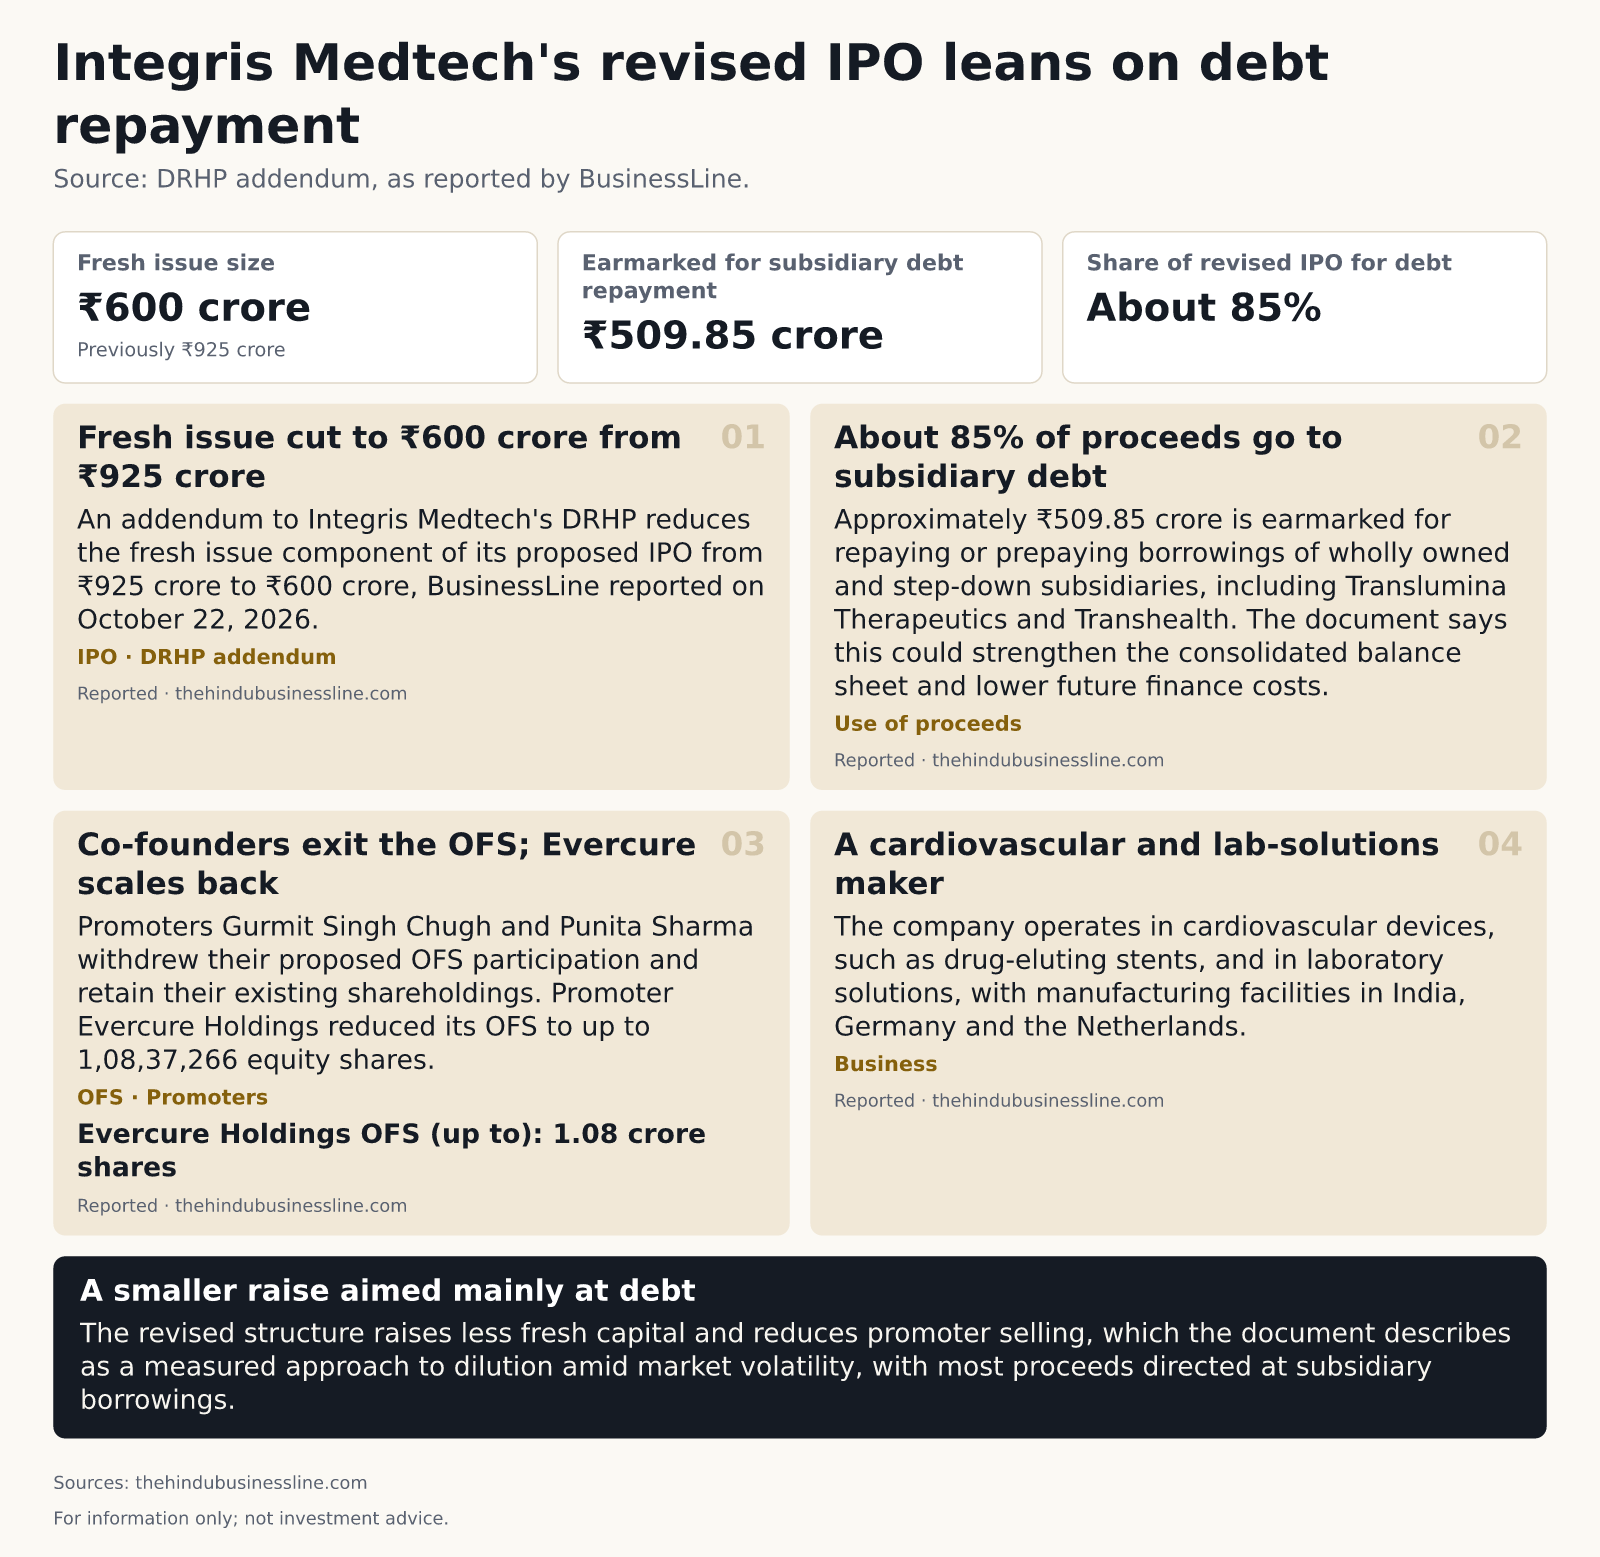
- Integris Medtech's proposed IPO now carries a ₹600 crore fresh issue, down from ₹925 crore, according to an addendum to its draft red herring prospectus (DRHP).
- About ₹509.85 crore of the new issue is earmarked for repaying or prepaying borrowings at subsidiaries such as Translumina Therapeutics and CPC Diagnostics.
- Co-founders Gurmit Singh Chugh and Punita Sharma have left the offer for sale. Promoter Evercure Holdings remains a seller of up to 1.08 crore shares, a reduced amount.
- The company links the revision to market volatility from geopolitical developments.
The filing raises two questions. What is the smaller issue now for? And who is still selling? The answer to the first is mostly debt. The answer to the second is one promoter entity rather than three promoters.
1. A smaller fresh issue now goes mostly to subsidiary debt
Reported: Integris Medtech has reduced the fresh issue component of its proposed IPO from ₹925 crore to ₹600 crore, according to the DRHP addendum. BusinessLine reported this on October 22, 2026. Approximately ₹509.85 crore is earmarked for repaying or prepaying borrowings across wholly owned and step-down subsidiaries. BusinessLine described this as about 85% of the revised IPO structure.
Our analysis: The fresh issue falls from ₹925 crore to ₹600 crore, a cut of ₹325 crore, or about 35%. Of the ₹600 crore, ₹509.85 crore goes to debt, which leaves a balance of about ₹90 crore. As a result, most of the new money would retire existing borrowings rather than fund expansion.
2. Two co-founders step out of the sale, and Evercure sells less
Reported: Promoters Gurmit Singh Chugh and Punita Sharma have withdrawn their proposed participation in the offer for sale (OFS). According to the addendum, this lets them retain their existing shareholdings through the transaction. Promoter Evercure Holdings Pte. Ltd has cut its proposed OFS to up to 1,08,37,266 equity shares, or about 1.08 crore shares. The document describes the restructuring as a measured approach to shareholder dilution and capital raising.
Our analysis: After the change, Evercure is the only promoter seller. The co-founders keep their full holdings into listing. The rupee value of Evercure's sale depends on the price band, which has not been announced.
3. The borrowings sit across the operating businesses
Reported: The addendum names five subsidiaries among those whose borrowings would be repaid:
- Translumina Therapeutics
- Transhealth
- CPC Diagnostics
- Chemopharm
- Research Instruments
The company works in two segments:
- Cardiovascular devices: drug-eluting stents, drug-coated balloons, complex coronary intervention products and vascular access solutions.
- Laboratory solutions: serving clinical, research and industrial labs.
It has manufacturing facilities in India, Germany and the Netherlands. Chugh and Sharma co-founded the company. It began by selling cardiology products and moved into manufacturing with technologies such as the Yukon drug-eluting stent.
Our analysis: The debt being repaid is spread across both the device and laboratory businesses. It is not held only at the parent company.
4. The company frames the cut as a response to volatility
Reported: The addendum describes the revision as a calibrated approach to raising capital amid evolving market conditions and heightened volatility from geopolitical developments. It says the company retains a significant focus on debt reduction. The document says the debt reduction could strengthen the consolidated balance sheet, lower future finance costs and give greater financial flexibility. BusinessLine noted that the proposed IPO follows the strong subscription of Sahajanand Medical Technologies' ₹475 crore IPO.
Our analysis: The lower finance costs and added flexibility are the company's expectations, not results. Whether they materialise depends on the issue completing and the stated borrowings being repaid.
What this means for readers
- The smaller offer is now largely a debt-repayment issue. Readers assessing it may weigh how much of the ₹600 crore is left after the ₹509.85 crore earmarked for subsidiary borrowings.
- The co-founders are not selling and Evercure's sale is smaller. This changes who exits at listing, but the price band will set what that exit is worth.
- The company's statements on lower finance costs are forward-looking and stated as possibilities.
What we are watching next
- The price band and total offer size, which will give a rupee value to Evercure's sale of up to 1.08 crore shares.
- How the balance of the ₹600 crore fresh issue, beyond the ₹509.85 crore for debt, is allocated in later offer documents.
- Progress of the DRHP through regulatory review after the addendum.